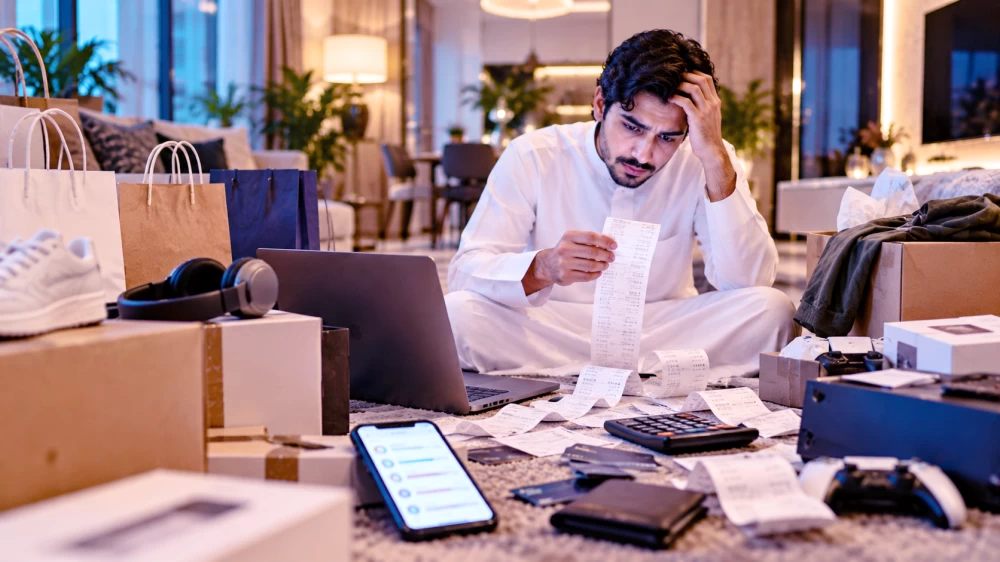
يختار المستهلك منتجاً من متجر إلكتروني، وعند إتمام الطلب تظهر أمامه إمكانية تقسيم المبلغ إلى دفعات صغيرة. يتراجع شعوره بارتفاع السعر، وتبدو عملية الشراء أكثر سهولة، وربما يضيف منتجاً آخر إلى السلة. لكن ما يبدو التزاماً محدوداً عند كل عملية شراء، قد يتحول مع تكرار التجربة إلى أعباء مالية متراكمة تتجاوز قدرة المستهلك على تقديرها.
وتعكس خدمات «اشترِ الآن وادفع لاحقاً» تحولاً في أنماط التمويل الاستهلاكي، بعدما أصبحت خيارات التقسيط جزءاً من تجربة التسوق اليومية، بدلاً من ارتباطها التقليدي بالمشتريات مرتفعة القيمة.
وتوفر هذه الخدمات مرونة في توزيع المدفوعات، وقد تساعد المستهلك على إدارة نفقاته عندما يستخدمها ضمن ميزانية واضحة. غير أن الإشكالية تبدأ حين تصبح الدفعة الشهرية، لا السعر الإجمالي، هي المعيار الذي يحدد قرار الشراء.
نفسياً، يقلل تقسيم المبلغ من الإحساس الفوري بكلفة الإنفاق، وقد يشجع على اتخاذ قرارات استهلاكية لم تكن لتحدث لو استوجب الشراء دفع القيمة كاملة. ومع تعدد العمليات، يجد المستهلك نفسه أمام التزامات صغيرة موزعة على مواعيد مختلفة، يصعب أحياناً إدراك مجموعها الحقيقي.
اقتصادياً، تستفيد المتاجر من تسهيل قرار الشراء وزيادة فرص إتمام الطلبات، فيما تتوسع شركات الدفع المؤجل في تقديم خدماتها عبر قطاعات استهلاكية متعددة. لكن هذه المعادلة تثير تساؤلات حول حدود التسويق المسؤول، ومدى وضوح الالتزامات والرسوم المحتملة أمام العملاء.
وتتجاوز المشكلة قدرة الفرد على السداد إلى ثقافة استهلاكية، قد تجعل الاقتراض لشراء الكماليات سلوكاً اعتيادياً، خصوصاً عندما يُقدَّم التقسيط بوصفه ميزة مجانية لا التزاماً مالياً مستقبلياً.
وتكمن المفارقة، في أن سهولة الدفع قد تحجب صعوبة الالتزام. فالمستهلك لا يواجه بالضرورة عبئاً كبيراً في عملية واحدة، وإنما في تراكم قرارات صغيرة اتخذها على فترات متقاربة.
وهنا يصبح السؤال الأهم: هل تمنح خدمات الدفع المؤجل المستهلك قدرة أكبر على إدارة أمواله، أم تمنح السوق قدرة أكبر على دفعه إلى الشراء؟
The consumer selects a product from an online store, and upon completing the order, the option to split the amount into smaller installments appears before them. Their feeling of the high price diminishes, and the purchasing process seems easier, perhaps even prompting them to add another product to the cart. However, what seems like a limited commitment with each purchase may, with repeated experiences, turn into accumulating financial burdens that exceed the consumer's ability to estimate.
The "Buy Now, Pay Later" services reflect a shift in consumer financing patterns, as installment options have become part of the daily shopping experience, rather than being traditionally associated with high-value purchases.
These services provide flexibility in payment distribution and may help consumers manage their expenses when used within a clear budget. However, the problem begins when the monthly payment, rather than the total price, becomes the criterion that determines the purchasing decision.
Psychologically, splitting the amount reduces the immediate sense of the cost of spending and may encourage consumer decisions that would not have occurred if the purchase required paying the full amount upfront. With multiple transactions, the consumer finds themselves facing small commitments spread across different dates, making it sometimes difficult to grasp their true total.
Economically, stores benefit from facilitating the purchase decision and increasing the chances of completing orders, while deferred payment companies expand their services across various consumer sectors. However, this equation raises questions about the limits of responsible marketing and the clarity of obligations and potential fees before customers.
The problem extends beyond an individual's ability to repay to a consumer culture that may make borrowing to buy luxuries a habitual behavior, especially when installment payments are presented as a free feature rather than a future financial commitment.
The paradox lies in the fact that the ease of payment may obscure the difficulty of commitment. The consumer does not necessarily face a significant burden in a single transaction but rather in the accumulation of small decisions made over close intervals.
Here, the most important question becomes: Do deferred payment services grant consumers greater ability to manage their money, or do they provide the market with greater ability to push them towards purchasing?