دخل سباق الذكاء الاصطناعي مرحلة تتجاوز المنافسة على النموذج الأفضل إلى اختبار مالي ضخم: هل تصل التطبيقات المربحة قبل أن تستنزف البنية التحتية رؤوس الأموال؟
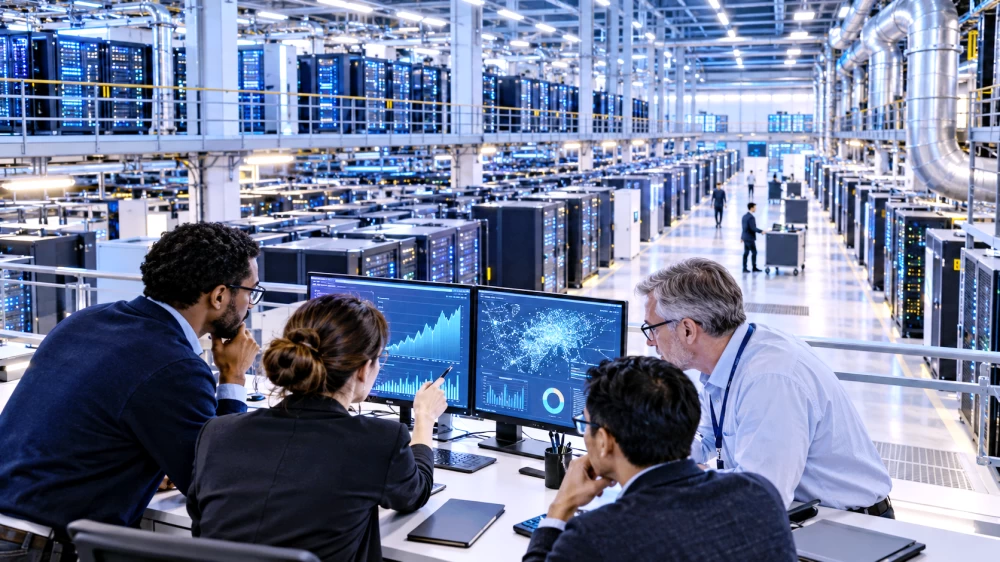
وتقدر «برايس ووترهاوس كوبرز»، تجاوز الإنفاق العالمي التراكمي على مراكز البيانات 30 تريليون دولار بحلول 2050، في موجة استثمارية تفوق، بالقيمة المعدلة، ما شهدته طفرتا السكك الحديدية والإنترنت. وتكشف الأرقام، أن الصناعة تبني قدرتها الحاسوبية على افتراض تحقيق قفزات واسعة في الإنتاجية، بينما ما تزال الأدلة الاقتصادية الشاملة محدودة.
ووفق دراسة لـ«باين»، تحتاج شركات الحوسبة العملاقة، ومنها «قوقل» و«أمازون» و«مايكروسوفت»، إلى أكثر من 4.2 تريليون دولار من الإيرادات الجديدة خلال خمسة أعوام لتمويل التوسع الجاري. وتشير التقديرات، كذلك، إلى حاجة قطاع الذكاء الاصطناعي الأمريكي إلى تحقيق إيرادات سنوية بنحو 3.55 تريليون دولار بحلول 2032، لضمان عائد استثماري يبلغ 10%، مقابل جزء محدود من ذلك حالياً. وتزداد صعوبة المعادلة مع اعتماد نسبة من المشاريع على الديون، وسرعة تقادم الرقائق، وارتفاع تكاليف الطاقة والتبريد. ويعني أي تأخر في الطلب أو انخفاض في قيمة الأصول تضاعف الخسائر المحتملة، خصوصاً في المشاريع التي بُنيت على توقعات نمو متفائلة.
التاريخ، مع ذلك، يقدم قراءة مزدوجة؛ فقد تعثرت شركات خلال طفرتي السكك الحديدية والإنترنت، لكن البنية التحتية التي تركتها واصلت دفع الاقتصاد لعقود. لذلك، لا يتعلق السؤال بانهيار الذكاء الاصطناعي، بل بمن يستطيع الصمود حتى تتحول القدرة الحاسوبية إلى إنتاجية وإيرادات فعلية.
The artificial intelligence race has entered a phase that goes beyond competing for the best model to a massive financial test: will profitable applications arrive before the infrastructure drains capital?
PricewaterhouseCoopers estimates that global cumulative spending on data centers will exceed $30 trillion by 2050, in an investment wave that, when adjusted for value, surpasses what was seen during the railway and internet booms. The figures reveal that the industry is building its computing capacity on the assumption of achieving significant leaps in productivity, while comprehensive economic evidence remains limited.
According to a study by Bain, giant computing companies, including Google, Amazon, and Microsoft, need more than $4.2 trillion in new revenue over five years to fund ongoing expansion. Estimates also indicate that the U.S. artificial intelligence sector needs to achieve annual revenues of about $3.55 trillion by 2032 to ensure a 10% return on investment, compared to a limited fraction of that currently. The equation becomes more challenging with a portion of projects relying on debt, the rapid obsolescence of chips, and rising energy and cooling costs. Any delay in demand or decline in asset values means potential losses could double, especially in projects built on optimistic growth forecasts.
History, however, offers a dual reading; companies stumbled during the railway and internet booms, but the infrastructure they left behind continued to drive the economy for decades. Therefore, the question is not about the collapse of artificial intelligence, but rather who can endure until computing capacity translates into actual productivity and revenues.