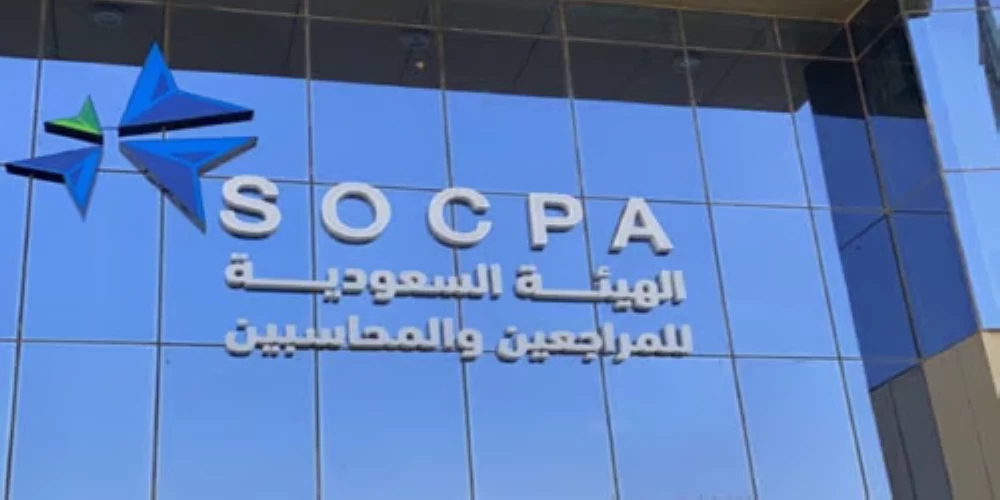
شددت الهيئة السعودية للمراجعين والمحاسبين على مسؤولية المحاسب القانوني عن التقارير والمعلومات المالية التي يصادق عليها، مؤكدة أن تصديق المحاسب القانوني على تقارير مالية لم يدققها هو أو من يعمل تحت إشرافه يعد من الجرائم المنصوص عليها في المادة العاشرة من نظام مهنة المحاسبة والمراجعة التي يعاقب كل من ارتكب واحدة أو أكثر منها بالسجن مدة لا تزيد على خمس سنوات وبغرامة لا تزيد على مليوني ريال أو بإحدى هاتين العقوبتين، وذلك دون إخلال بأي عقوبة ينص عليها نظام آخر.
وبينت أن المادة تجرم كذلك تقديم بيانات غير صحيحة أو شهادات مزورة للحصول على الترخيص وتضليل الجمهور بأي وسيلة بشأن الحق في مزاولة المهنة وتقديم المحاسب القانوني بيانات كاذبة أو إخفاء بيانات واجبة الإظهار مع علمه بذلك والتصديق على تقرير مخالف للحقيقة أو على وقائع غير حقيقية في مستند يتوجب إصداره نظامًا أو بمقتضى متطلبات مزاولة المهنة وإفشاء أسرار المنشأة التي يقدم خدماته إليها وتقديم معلومات غير صحيحة عن مؤهلات موظفيه وخبراتهم أو الإسهام في تقديمها.
وقال الرئيس التنفيذي للهيئة الدكتور أحمد المغامس: «إن موثوقية التقارير المالية تمثل عنصرًا أساسيًا في الصحة المالية وحماية المنشآت والمستفيدين ومستخدمي القوائم المالية»، مؤكدًا أن تكامل أدوار الهيئة ضمن منظومة المحاسبة والمراجعة مع الجهات الرقابية والقضائية يسهم في رفع مستوى الالتزام وضبط الممارسات غير النظامية؛ بما يعزز نزاهة المعلومات المالية وجودة الخدمات المهنية.
يشار إلى أن الهيئة أحالت منذ مطلع العام الحالي سبعة أفراد ومنشآت إلى النيابة العامة بعد أن كشفت إجراءات الرصد والاستدلال الأولية عن أفعال تدخل ضمن الجرائم المنصوص عليها في المادة العاشرة من نظام مهنة المحاسبة والمراجعة.
The Saudi Authority for Auditors and Accountants emphasized the responsibility of the certified public accountant for the reports and financial information they certify, confirming that the certification by a certified public accountant on financial reports that have not been audited by them or by those working under their supervision is considered one of the crimes stipulated in Article Ten of the Accounting and Auditing Profession Law, for which anyone committing one or more of these offenses can be punished with imprisonment for a period not exceeding five years and a fine not exceeding two million riyals, or one of these penalties, without prejudice to any other penalties stipulated by another law.
It clarified that the article also criminalizes the submission of incorrect data or forged certificates to obtain a license and misleading the public by any means regarding the right to practice the profession, and the certified public accountant providing false data or concealing information that must be disclosed, knowing this, and certifying a report that is contrary to the truth or on untrue facts in a document that must be issued by law or under the requirements of practicing the profession, and disclosing the secrets of the establishment to which they provide services and providing incorrect information about the qualifications of their employees and their experiences or contributing to providing it.
The CEO of the authority, Dr. Ahmed Al-Mughamis, stated: "The reliability of financial reports represents a fundamental element in financial health and the protection of establishments, beneficiaries, and users of financial statements," emphasizing that the integration of the authority's roles within the accounting and auditing system with regulatory and judicial bodies contributes to raising the level of compliance and controlling irregular practices; thus enhancing the integrity of financial information and the quality of professional services.
It is worth noting that the authority has referred seven individuals and establishments to the Public Prosecution since the beginning of this year after initial monitoring and investigation procedures revealed actions that fall within the crimes stipulated in Article Ten of the Accounting and Auditing Profession Law.